Skip to Content
FDIC-Insured - Backed by the full faith and credit of the U.S. Government

SBA Lending. Without the Runaround.

7(a) and 504 programs, handled by local people you can actually reach.

SBA financing can be one of the most powerful tools for small businesses: lower down payments, longer terms, and access to capital conventional programs can't always provide. We'll tell you which program fits and what to expect, before you're deep into paperwork.

Talk to an SBA Lender

Is an SBA 7(a) loan right for me?

Eligibility criteria

SBA 7(a) financing works for a wide range of businesses — retail, manufacturing, professional services, restaurants, and more. If the items below describe your business, a 7(a) loan may be a fit.
  • Operates as a for-profit business in the United States
  • Meets SBA size standards for its industry
  • 100% owned by U.S. citizens or U.S. nationals residing in the United States
  • Demonstrates ability to repay from business cash flow
  • Owners meet SBA creditworthiness standards, including personal credit history
  • Has equity to contribute — generally 10% of total project cost for startups and changes of ownership

Common questions

What's the difference between 7(a) and 504?

7(a) is the most flexible option: it covers the widest range of uses. 504 is purpose-built for fixed assets like real estate and major equipment. 

An SBA loan is a business loan backed in part by the U.S. Small Business Administration (SBA). This backing helps lenders offer financing with flexible terms and, in some cases, lower down payments than conventional business loans. Depending on the program, funds can be used to purchase commercial real estate or equipment, acquire a business, or support everyday operations and growth.


Working capital, equipment, inventory, owner-occupied commercial real estate, leasehold improvements, business acquisition, and in some cases refinancing existing business debt.

Borrowers can access up to $5 million through the SBA 7(a) program. For SBA 504 loans, the SBA-backed portion can reach $5 million, with limits of $5.5 million for eligible manufacturing and energy projects.

No. We work with businesses across Tampa Bay whether or not you bank with us.

Garrett VonEye handles SBA lending directly. No call center, no intake queue. His contact information is below, or use the form on this page.

Resources

Plan Before You Borrow

Reference materials for business owners planning a loan or buildout.

SBA LENDING

SBA 7(a) Checklist

What to expect at each phase, from term sheet to closing.

Download PDF

restaurants

Opening a Restaurant: Costs to Consider

The startup expenses that catch new owners off guard.

Download PDF

construction

Construction and Leasehold Improvements

What's in your GC contract, and what isn't.

Download PDF

Talk to an SBA Lender

Tell us a bit about your business and what you're looking to finance. One of us will reach out within one business day.

Prefer to talk now? Reach out to us directly, or stop by any of our offices in Feather Sound, Bayshore, or Tarpon Springs.
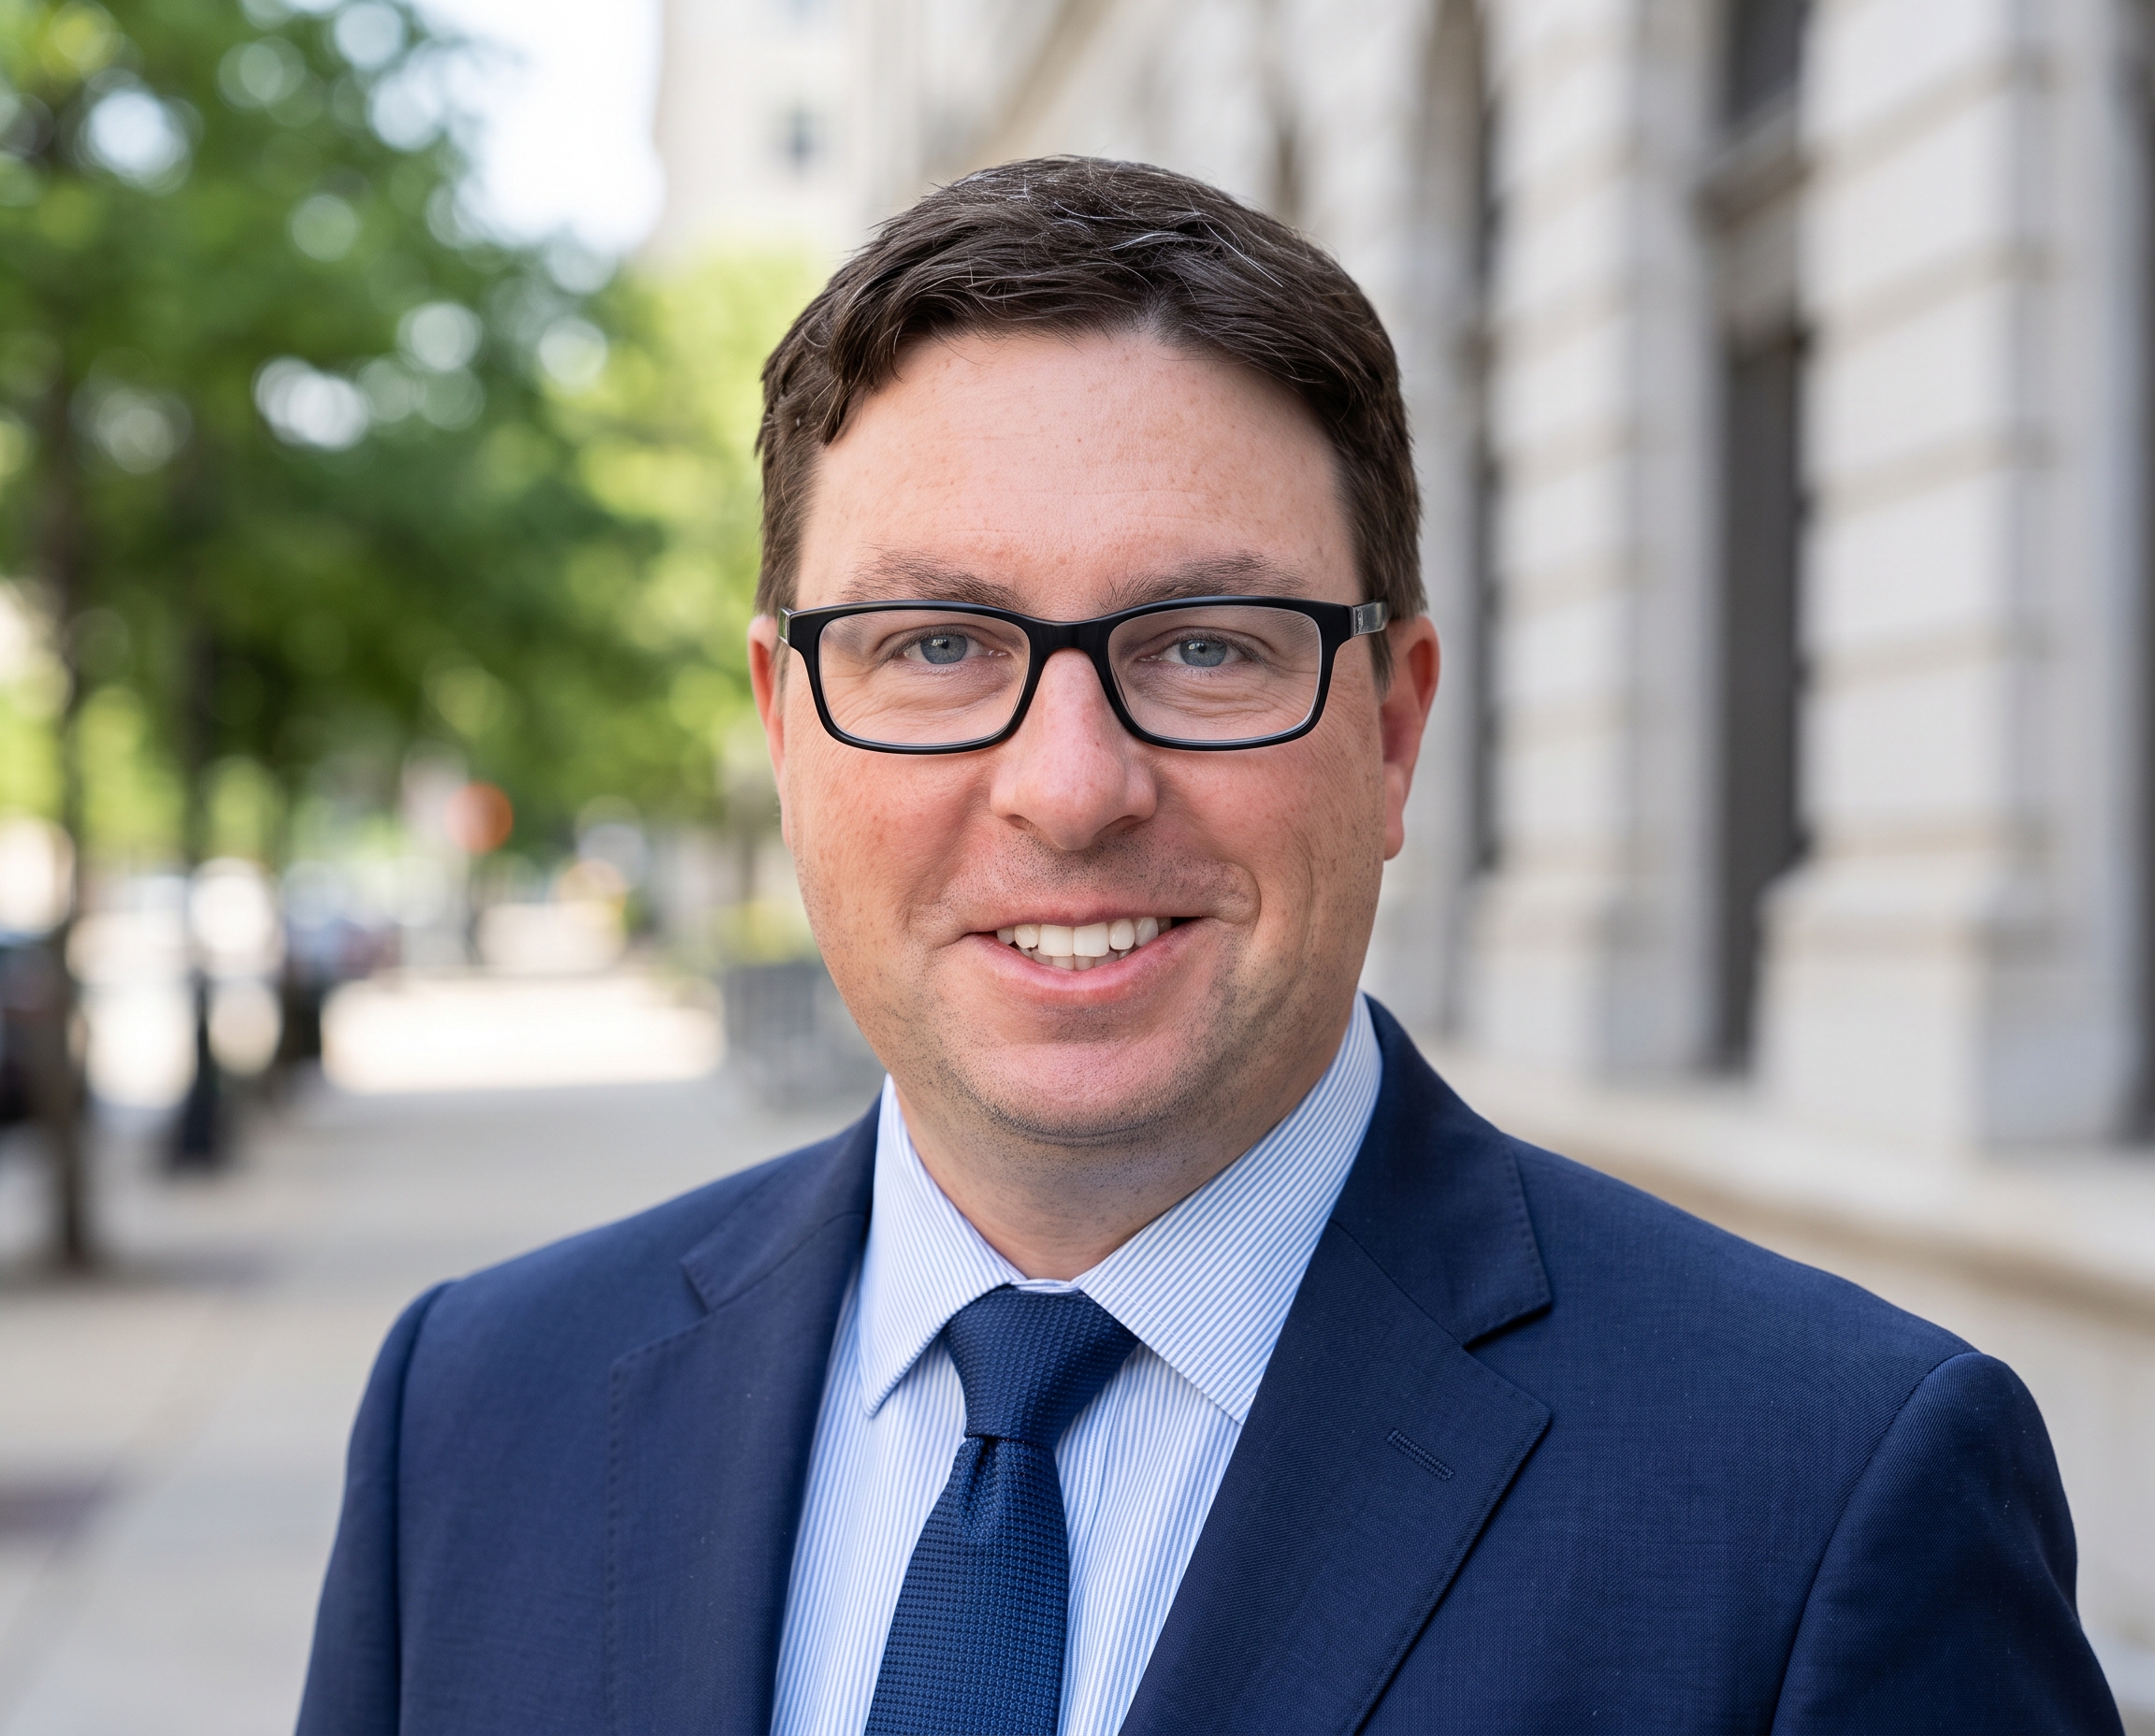
Garrett VonEye, SVP Director of SBA Lending at Echelon Bank

Garrett VonEye

Director of SBA Lending

[email protected]

Have your basics handy: how long you've been in business, roughly what you're looking to borrow, and what the funds are for.
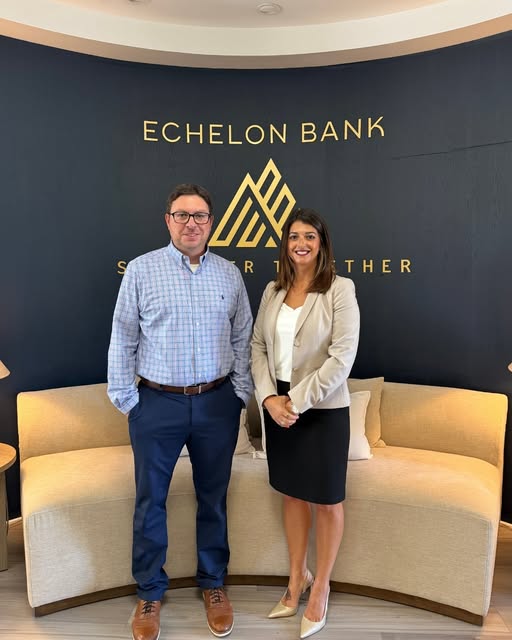
Garrett VonEye, SVP Director of SBA Lending & Ashley Benoit, SVP, Director of SBA Administration